Your early twenties are a whirlwind of major life changes. You are likely navigating your first professional job, managing rent for your own flat, and suddenly realising that the world of personal finance is entirely your responsibility. Whilst it is tempting to spend your newfound income on holidays and weekend socialising, the financial habits you build now will dictate your wealth for decades to come.
If you want to set yourself up for long-term freedom, you need a game plan. We have put together the ultimate Financial Level-Up Checklist: 20 Money Moves Before 25to help you build a bulletproof financial foundation. Let’s dive straight into the actions you need to take.
Phase 1: Master Your Cash Flow
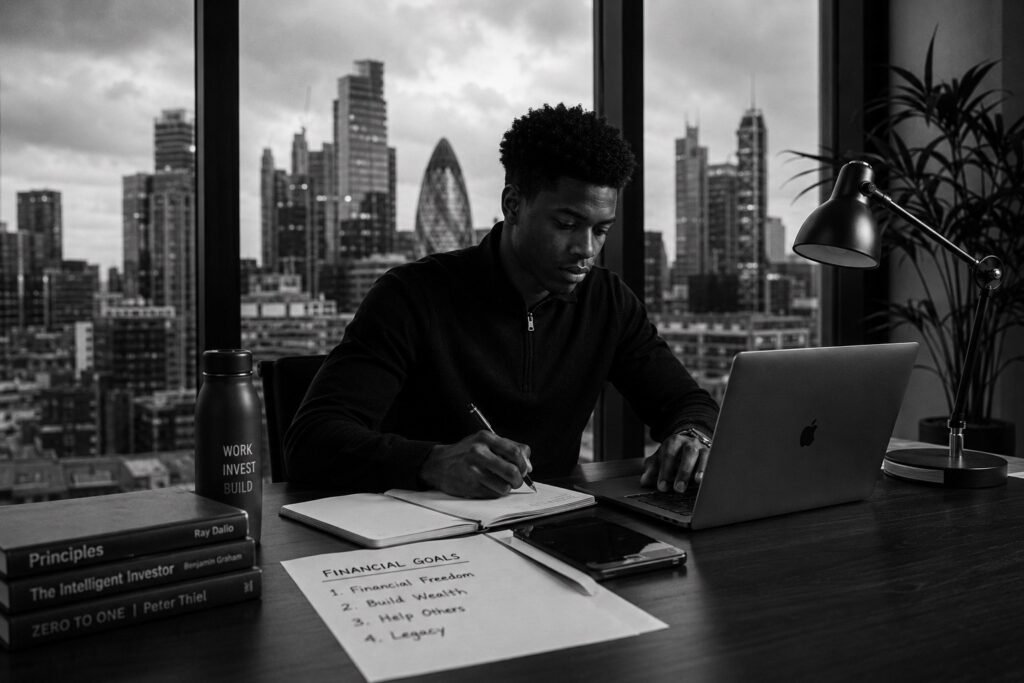
Before you can start building serious wealth, you need to understand exactly where your money is going.
1. Master the 50/30/20 Rule
Budgeting does not mean stopping all your spending; it means spending with intention. If you are unsure how to create a 50/30/20 budget, it is incredibly straightforward. You simply allocate 50% of your after-tax income to needs (rent, groceries, bills), 30% to wants (dining out, entertainment), and 20% to savings and investments. This structure gives you the freedom to enjoy your youth whilst securing your future.
2. Build Your Safety Net
Life is unpredictable. Cars break down, and unexpected medical bills arise. When figuring out how much emergency fund for young adults is truly necessary, aim for three to six months’ worth of essential living expenses. Keep this cash accessible so you never have to rely on high-interest credit cards when a crisis strikes.
3. Upgrade Your Savings Strategy
Keeping your cash in a standard current account means you are losing money to inflation. When comparing a high yield savings account vs traditional savings, the difference is staggering. High-yield accounts, often offered by online banks, provide significantly higher interest rates, allowing your emergency fund to grow passively without any extra effort on your part.
4. Track Your Net Worth
Your net worth is simply everything you own (assets) minus everything you owe (liabilities). Many wonder what is a good net worth by 25. The truth? Merely crossing from a negative number into a positive one is a fantastic achievement at this age. Tracking this figure annually gives you a clear, realistic picture of your financial trajectory.
5. Set Clear Objectives
Without a target, you will drift financially. Establishing clear financial goals for college graduates and university leavers—such as saving a deposit for a house, funding a gap-year trip, or achieving debt freedom—gives your money purpose and helps you stay disciplined when temptation strikes.
Phase 2: Conquer Debt and Build Credit
Your credit history is your financial passport. It affects your ability to secure a mortgage, rent a flat, and occasionally even land a job.
6. Understand the Power of Your Credit Score
A strong credit score proves to lenders that you are a reliable borrower. Familiarise yourself with the main credit reference agencies and check your report regularly for errors. A good score will unlock the best interest rates, saving you thousands over your lifetime.
7. Start the Clock on Your Credit History
One of the best moves you can make is building credit score in your early 20s. You can achieve this by opening a starter credit card, using it for small monthly purchases like your phone bill, and paying the balance off in full by direct debit every single month.
8. Crush High-Interest Debt
If you have accumulated credit card debt, it should be your top priority. Research different credit card debt repayment strategies, such as the “debt avalanche” (paying off the highest interest rate first) or the “debt snowball” (paying off the smallest balance first for a psychological win). Choose the strategy that keeps you motivated and stick to it relentlessly.
9. Create a Student Loan Strategy
Student loans can feel like a massive burden, but they do not have to hold you back. When managing student loan debt after graduation, understand the specific terms of your loan. In many systems, repayments are income-contingent. Calculate whether it makes sense to pay them off aggressively or simply make the minimum monthly contributions whilst investing your remaining cash.
Phase 3: Demystify Investing
You cannot save your way to wealth; you must invest. The earlier you start, the less of your own money you have to contribute, thanks to the magic of time in the market.
10. Grasp the Fundamentals
Before risking your hard-earned pounds, take an afternoon to learn investment basics. Understand the difference between equities (stocks), bonds, and cash. Knowing your risk tolerance and investment timeline is the foundation of a robust portfolio.
11. Learn the Magic of Compounding
Albert Einstein allegedly called compound interest the eighth wonder of the world. Understanding compound interest for beginners is crucial: it is simply the process of earning interest on your interest. A small amount of money invested at age 22 will grow exponentially larger than a massive sum invested at age 40.
12. Choose the Right Investment Vehicles
The financial industry loves to make investing sound complicated, but it doesn’t have to be. When looking at an index fund vs individual stock investing, index funds almost always win for the everyday investor. They offer broad market diversification and low fees, whereas picking individual stocks is highly risky and time-consuming.
13. Open a Tax-Advantaged Retirement Account
Governments heavily incentivise saving for retirement. For those with US financial ties, the benefits of starting a Roth IRA early are monumental, as your investments grow completely tax-free. If you are in the UK, a Lifetime ISA (LISA) or a Stocks and Shares ISA provides similar brilliant tax wrappers. Fill these accounts as early as you can.
14. Claim Your Free Money
If your workplace offers a pension scheme, enrol immediately. Getting an employer 401k match explained (or a UK workplace pension match) is simple: if you contribute a certain percentage of your salary, your employer will match it. This is quite literally free money and an instant 100% return on your investment. Never leave it on the table.
15. Put Your Wealth on Autopilot
Willpower is a finite resource. Remove the temptation to spend by setting up automatic investment transfers. Have a portion of your pay cheque automatically routed to your investment and savings accounts the day after you are paid. Paying yourself first guarantees that your wealth continues to grow in the background.
Phase 4: Maximise Earnings and Protect Your Wealth
Frugality has a limit, but your earning potential does not. Your twenties are the time to boost your income and protect the assets you are building.
16. Utilise Health and Tax Benefits
If you have access to international or specialised healthcare accounts, take full advantage. Maximising health savings account benefits (HSAs) is a brilliant move, as they often offer a triple-tax advantage: contributions are tax-deductible, growth is tax-free, and withdrawals for medical expenses are untaxed. Even if you are healthy now, building this fund is a superb safety net.
17. Broaden Your Horizons
Relying solely on one employer can be risky. Focus on diversifying income streams in early career. Whether it is starting a freelance side hustle, selling digital products, or picking up weekend shifts, multiple streams of income accelerate your savings rate and provide immense financial security.
18. Learn to Negotiate Your Salary
Do not accept the first offer without doing your research. Your starting salary often dictates your future raises, bonuses, and pension contributions. Learn to articulate your value and politely negotiate your compensation. A £5,000 increase at age 23 could result in hundreds of thousands of pounds over the course of your career.
19. Avoid Lifestyle Creep
As your income grows, it is incredibly easy to justify a more expensive car, designer clothes, or a luxury flat. This is known as lifestyle inflation. Whilst you should absolutely enjoy the fruits of your labour, aim to save and invest at least 50% of every raise or bonus you receive.
20. Review and Adjust Regularly
Your life will change drastically between the ages of 20 and 25. What works for you at 21 might not suit your circumstances at 24. Make it a habit to schedule a quarterly financial review. Use a comprehensive financial checklist for young adults to ensure you are staying on track, rebalancing your portfolio, and adjusting your goals as your career progresses.
Final Thoughts
Taking control of your finances in your early twenties is one of the greatest gifts you can give to your future self. You do not need to be a mathematical genius or a Wall Street trader to build wealth. By working through this checklist, mastering your budget, avoiding bad debt, and investing consistently, you will build a life of financial freedom and independence. Start today, stay disciplined, and watch your net worth level
